Direct vs. Regular Mutual Funds: Which One Wins Your Investment Battle?
Direct mutual funds skip the distributor commission, so their expense ratio runs roughly 0.4–0.6 percentage points lower than the same fund's regular plan. On a ₹10,000/month SIP, that gap alone is worth about ₹76,000 extra over 10 years and over ₹7.4 lakh extra over 20 years. Regular plans still make sense if you genuinely want ongoing advice and behavioural coaching — just know what you're paying for it.
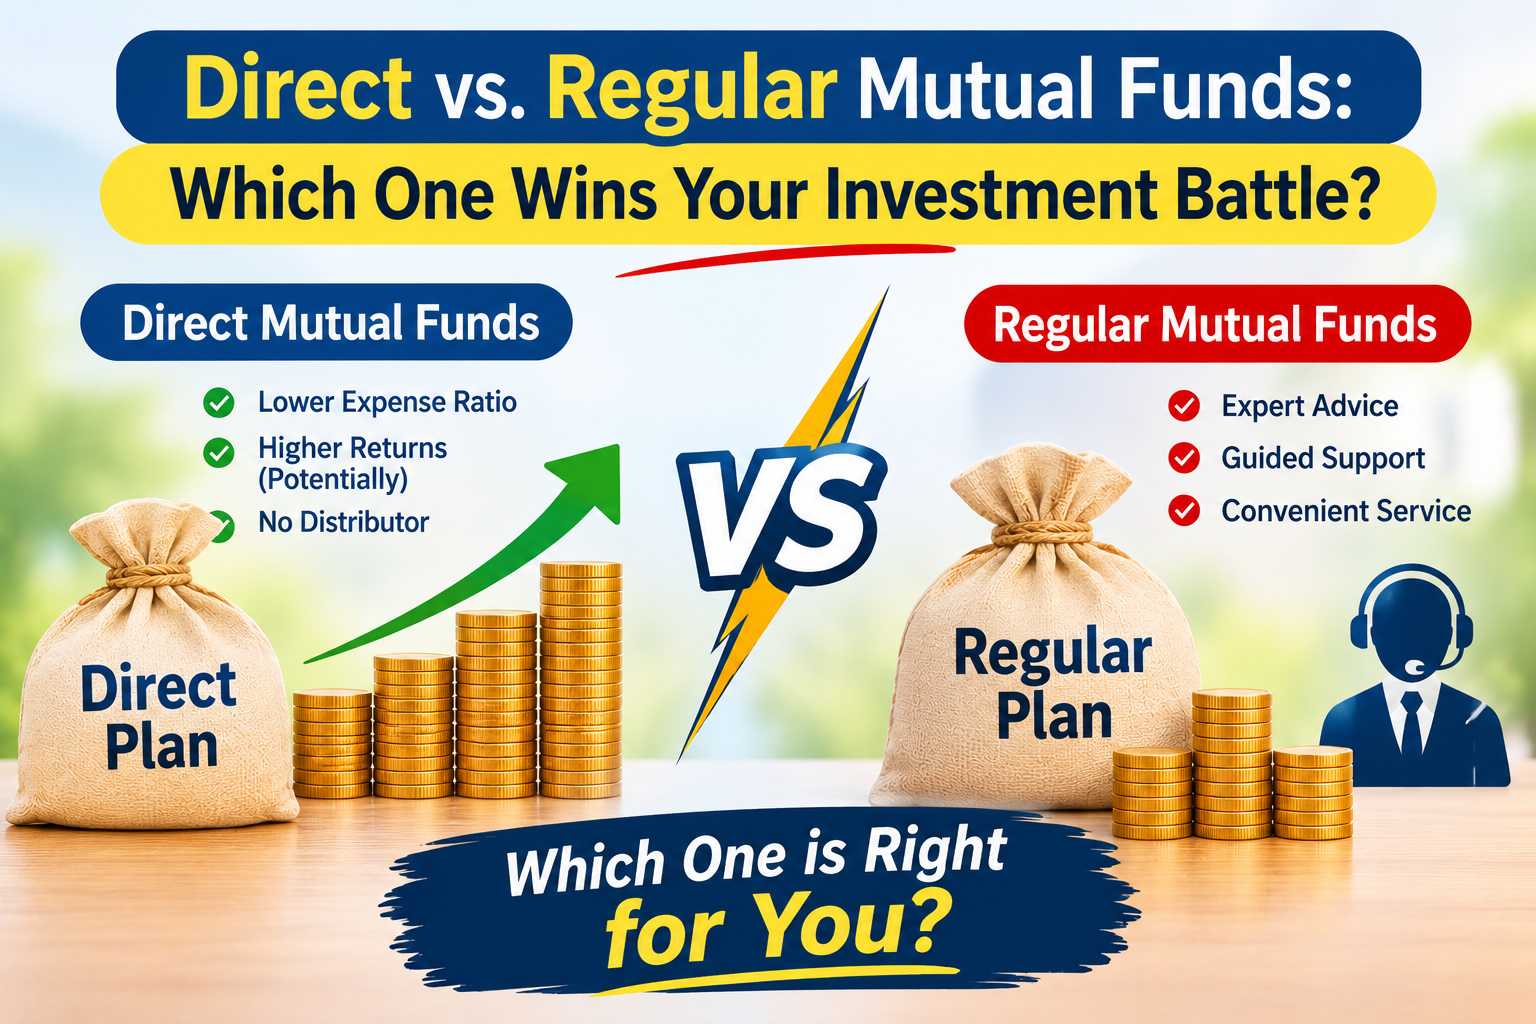
Direct vs Regular Mutual Funds: Which One Wins Your Investment Battle?
Mutual fund distributors have replaced the door-to-door insurance agent of decades past, and the pitch usually sounds personal: a recommended fund, a bit of hand-holding. What rarely gets mentioned is the ongoing cost of that service — a slice of your returns, every year, for as long as you stay invested. Here's what the direct vs regular mutual funds choice actually costs you, in real rupees.
Quick answer, if you're in a hurry: Direct mutual funds skip the distributor commission, so their expense ratio runs roughly 0.4–0.6 percentage points lower than the same fund's regular plan. On a ₹10,000/month SIP, that gap alone is worth about ₹76,000 extra over 10 years and over ₹7.4 lakh extra over 20 years. Regular plans still make sense if you genuinely want ongoing advice and behavioral coaching — just know what you're paying for it. |
What's the Actual Difference Between Direct vs Regular Mutual Funds?
Every mutual fund scheme is sold in two versions holding the exact same portfolio — same stocks or bonds, same fund manager, same market performance. Only the distribution channel, and the fee, differ.
Regular Plans: Bought through a distributor or advisor, who earns an ongoing trail commission built into the expense ratio.
Direct Plans: Bought straight from the AMC or an online investing platform, with no distributor involved.
What you give up: Regular plans include a human advisor for guidance; direct plans leave research and decisions to you.
Expense Ratios: Where the Gap Really Comes From
The expense ratio is the annual fee, deducted daily from fund assets, covering fund management and, for regular plans, distributor commissions. Take the HDFC Mid-Cap Opportunities Fund, one of India's largest equity schemes, with an AUM of roughly ₹1.02 lakh crore as of October 2026.
Plan | Expense Ratio | What It Means |
Regular Plan | ~1.31% p.a. | Includes distributor commission |
Direct Plan | ~0.76% p.a. | No intermediary fee |
That's roughly 0.55 percentage points more per year for the regular plan — about 70% costlier than the direct version, not quite "double" but still a meaningful, compounding drag. Since both track an identical portfolio, every rupee saved in fees stays invested and keeps compounding.
How Much Does This Actually Cost You Over Time?
Expense ratios sound small on paper, but compounded over years, the gap widens sharply. Here's a ₹10,000/month SIP in each plan, assuming a 13% gross market return:
SIP Duration | Direct Plan Corpus | Regular Plan Corpus | You Gain by Going Direct |
5 years | ₹8.30 lakh | ₹8.18 lakh | ₹12,513 |
10 years | ₹23.57 lakh | ₹22.81 lakh | ₹75,902 |
20 years | ₹1.03 crore | ₹95.82 lakh | ₹7,41,020 |

₹10,000/month SIP over 20 years, same fund: the direct plan's lower cost compounds into a meaningfully larger corpus. Figures are illustrative, based on a 13% assumed gross return.
When Does a Regular Plan Actually Make Sense?
Direct plans win on cost, but that doesn't make regular plans pointless. They can be the right call if:
You genuinely don't have time to research, track, or rebalance funds yourself.
You tend to panic-sell during downturns, and an advisor's guidance stops costly, emotion-driven decisions.
You'd rather trade a fraction of your returns for ongoing hand-holding — a legitimate preference, not a mistake.
How to Decide
Comfortable picking funds and staying invested through volatility without hand-holding? Direct plans are the lower-cost choice for identical exposure. Want someone to call during a crash, or know you won't keep up on your own? A regular plan through a trustworthy advisor is reasonable — just treat the extra fee as the price of that service, and confirm you're actually getting it.
Frequently Asked Questions
Do direct and regular plans of the same fund earn different returns from the market?
No — both hold the identical portfolio and see the same gross market performance. The only difference is the expense ratio deducted before you see your returns, which is why direct plans end up with a higher NAV and larger final corpus.
Can I switch from a regular plan to a direct plan later?
Yes, though it's usually treated as redemption-and-reinvestment, which can trigger capital gains tax and, for equity funds, exit load within the exit-load period. Check both before switching.
Is the expense ratio the only cost difference?
Essentially, yes. Both plans carry the same fund-level transaction costs; the expense ratio gap is almost entirely the distributor commission built into the regular plan.
The Bottom Line
Direct and regular plans deliver the same market performance from the same fund — the expense ratio is the only real difference, and it compounds. Over 20 years on a modest SIP, that gap alone can be worth several lakh rupees. Willing to do your own research? Direct plans are hard to beat on cost. Need a guide along the way? A regular plan isn't wrong — just know what the fee buys.
Disclaimer This article is for general information only, not personalized financial or tax advice. Mutual fund investments are subject to market risks; expense ratios and AUM figures change over time and should be verified on the AMC's website before investing. Consult a certified financial advisor before making investment decisions. |