Mutual Fund Diversification: How Many Funds Do You Need?
Most investors need just 6–7 well-chosen funds across different categories and fund houses — not 15. Beyond that, you're mostly adding portfolio overlap (funds quietly holding the same stocks) rather than real diversification. What matters more than fund count is spreading across asset classes that don't move together, like equity, debt, and gold.
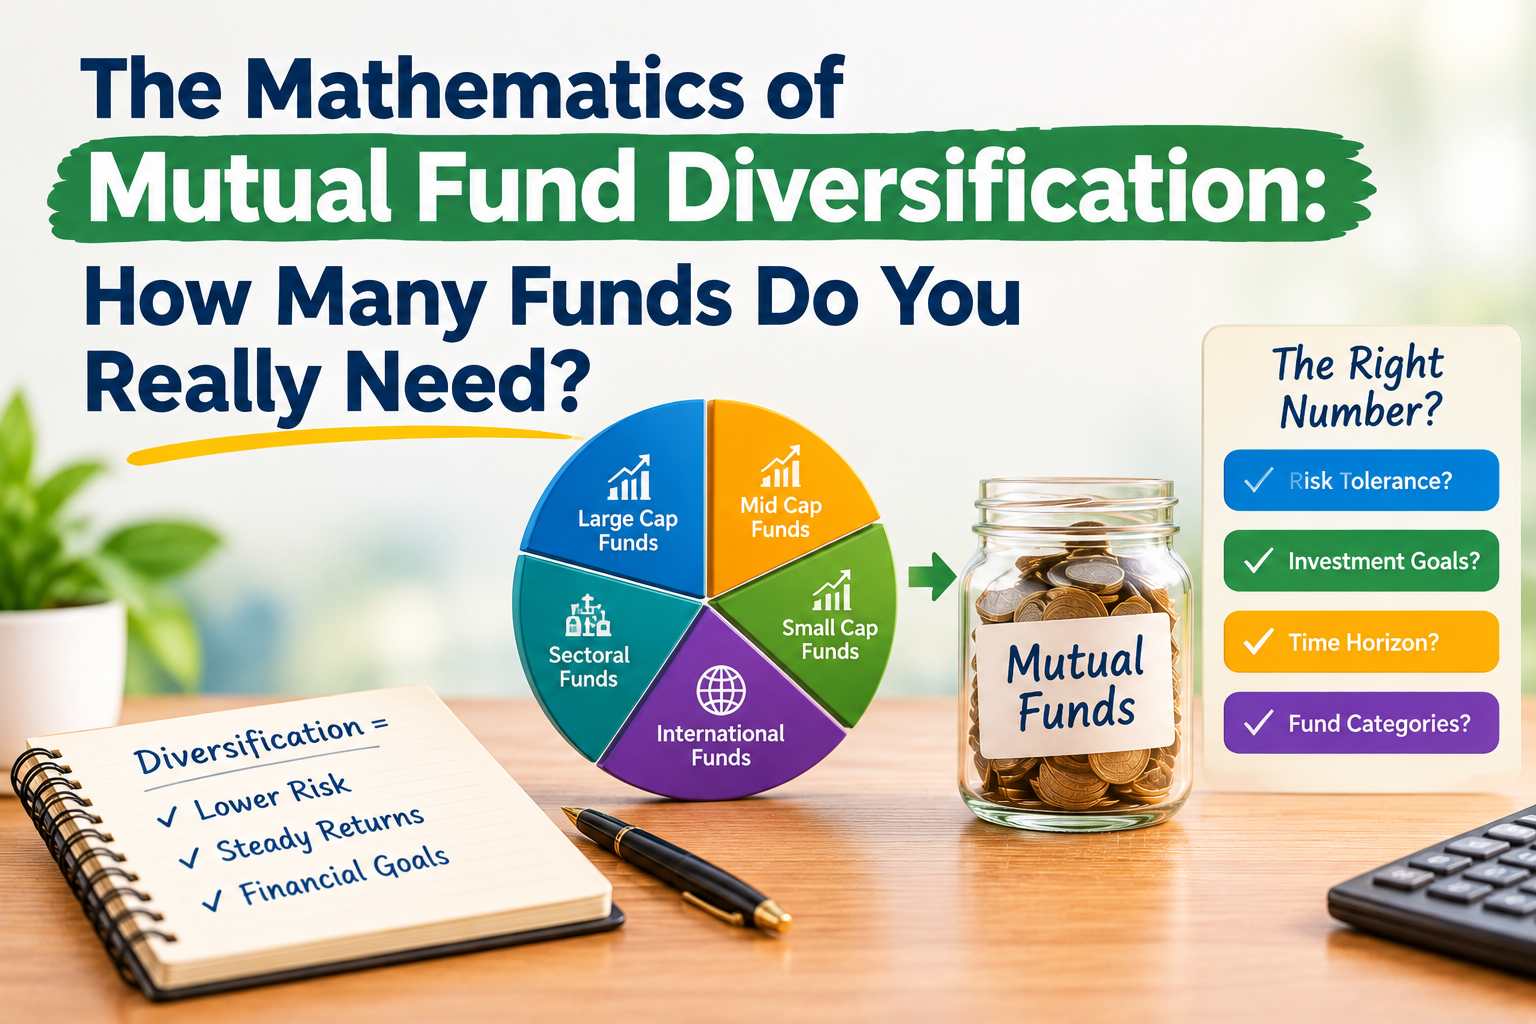
The Mathematics of Mutual Fund Diversification: How Many Funds Do You Really Need?
If you've been collecting mutual funds the way some people collect stamps, you're not alone — and you're probably not as diversified as you think. Owning 12 or 15 funds doesn't automatically spread your risk. Past a point, it just means more paperwork and funds quietly holding the same stocks. Here's what real mutual fund diversification looks like, and how many funds you actually need.
Quick answer, if you're in a hurry: Most investors need just 6–7 well-chosen funds across different categories and fund houses — not 15. Beyond that, you're mostly adding portfolio overlap (funds quietly holding the same stocks) rather than real diversification. What matters more than fund count is spreading across asset classes that don't move together, like equity, debt, and gold. |
What Diversification Actually Means
True diversification isn't about owning more funds — it's about owning funds that behave differently from each other. Spread your money across sectors, company sizes, and asset classes, and when one part of your portfolio dips, another can hold steady or even rise, smoothing out your overall ride.
The real goal is a better risk-adjusted return — the return you earn per unit of risk you take on, not just the raw number on your statement.
Risk vs Return: Finding Your Balance
Equity funds (especially small-cap or high-beta ones): bigger gains in bull markets, bigger falls in corrections.
Conservative, debt-heavy allocations: steadier, but may barely outrun inflation over time.
Your life stage matters: younger investors can typically absorb more equity risk; those nearing a goal usually need more stability.
Why Asset Correlation Is the Real Diversification Tool
Correlation measures whether two investments move together or in opposite directions. This matters more for diversification than simply owning more funds:
Correlation Type | Example | What It Does for You |
Positive | Equities and real estate often move together | Offers little extra protection |
Negative | Equities and gold often move apart | Cushions your portfolio when one side falls |
Holding some negatively correlated assets, like gold or high-quality debt alongside equity, acts like insurance: when markets fall, these holdings can hold their value or even rise, softening the blow.
How Many Funds Should You Actually Hold?
Many investors pile up 10–15 funds across overlapping categories, assuming more funds means more safety. In reality, it usually just means portfolio overlap — multiple funds quietly holding the same large-cap stocks, so you're paying extra fund fees without any real diversification benefit.

The diversification benefit of adding funds flattens out fast — while the risk of overlapping holdings keeps climbing the more you add.
A lean portfolio of 6–7 core funds usually covers what you need:
2–3 funds per major category (like flexi-cap or large-cap) — not more.
Managers with different styles — mix growth-focused and value-focused funds to reduce overlap.
A small slice (10%–20%) for thematic or sector bets, only if you're actively tracking them.
Fewer Funds, Spread Wider: Single Fund vs Multi-Asset
If juggling equity, debt, and gold yourself feels like a lot, multi-asset allocation funds do it for you in one scheme, automatically rebalancing across asset classes.
What Matters | DIY Multi-Fund Portfolio | Multi-Asset Allocation Fund |
You do it manually | Done automatically by the fund manager | |
Effort required | Higher — tracking several schemes | Lower — one scheme, one NAV to track |
Behavioral risk | Easier to panic-sell in a downturn | Built-in discipline reduces emotional decisions |
How These Funds Are Taxed
Tax treatment depends on how much of the fund sits in equity, not its name:
Fund Type | How It's Taxed |
Equity-oriented (65%+ in equity), held over 12 months | Flat 12.5% LTCG, first ₹1.25 lakh/year tax-free |
Equity-oriented (65%+ in equity), held 12 months or less | 20% STCG |
Debt-oriented / most multi-asset funds (under 65% equity) | Your income tax slab rate, any holding period |
Check a multi-asset fund's actual equity allocation before investing — it decides which row above applies to you.
Frequently Asked Questions
Is holding more mutual funds always better for diversification?
No. Beyond 6–7 well-chosen funds, you're usually just adding portfolio overlap — multiple schemes holding the same stocks — rather than real diversification.
What's the ideal number of mutual funds for a retail investor?
Most financial planners suggest 6–7 core funds spread across categories and fund houses, with small thematic bets kept separate and limited.
Are multi-asset funds a good alternative to building your own mix?
They can be, especially if you don't want to manually rebalance. You trade some control for automatic diversification and built-in discipline.
The Bottom Line
Diversification is about owning things that don't all fall together, not about owning everything. A focused portfolio of 6–7 funds across genuinely different categories, plus a slice of a low-correlation asset like gold or debt, usually beats a drawer full of 15 overlapping schemes — with far less to track.
Disclaimer This article is for general information only, not personalized financial or tax advice. Tax rules change. Consult a certified financial advisor before restructuring your portfolio. |