Best SIP Plan: A Step-by-Step Guide to Risk-Adjusted Wealth Creation
Best SIP Plan: A Step-by-Step Guide to Risk-Adjusted Wealth Creation
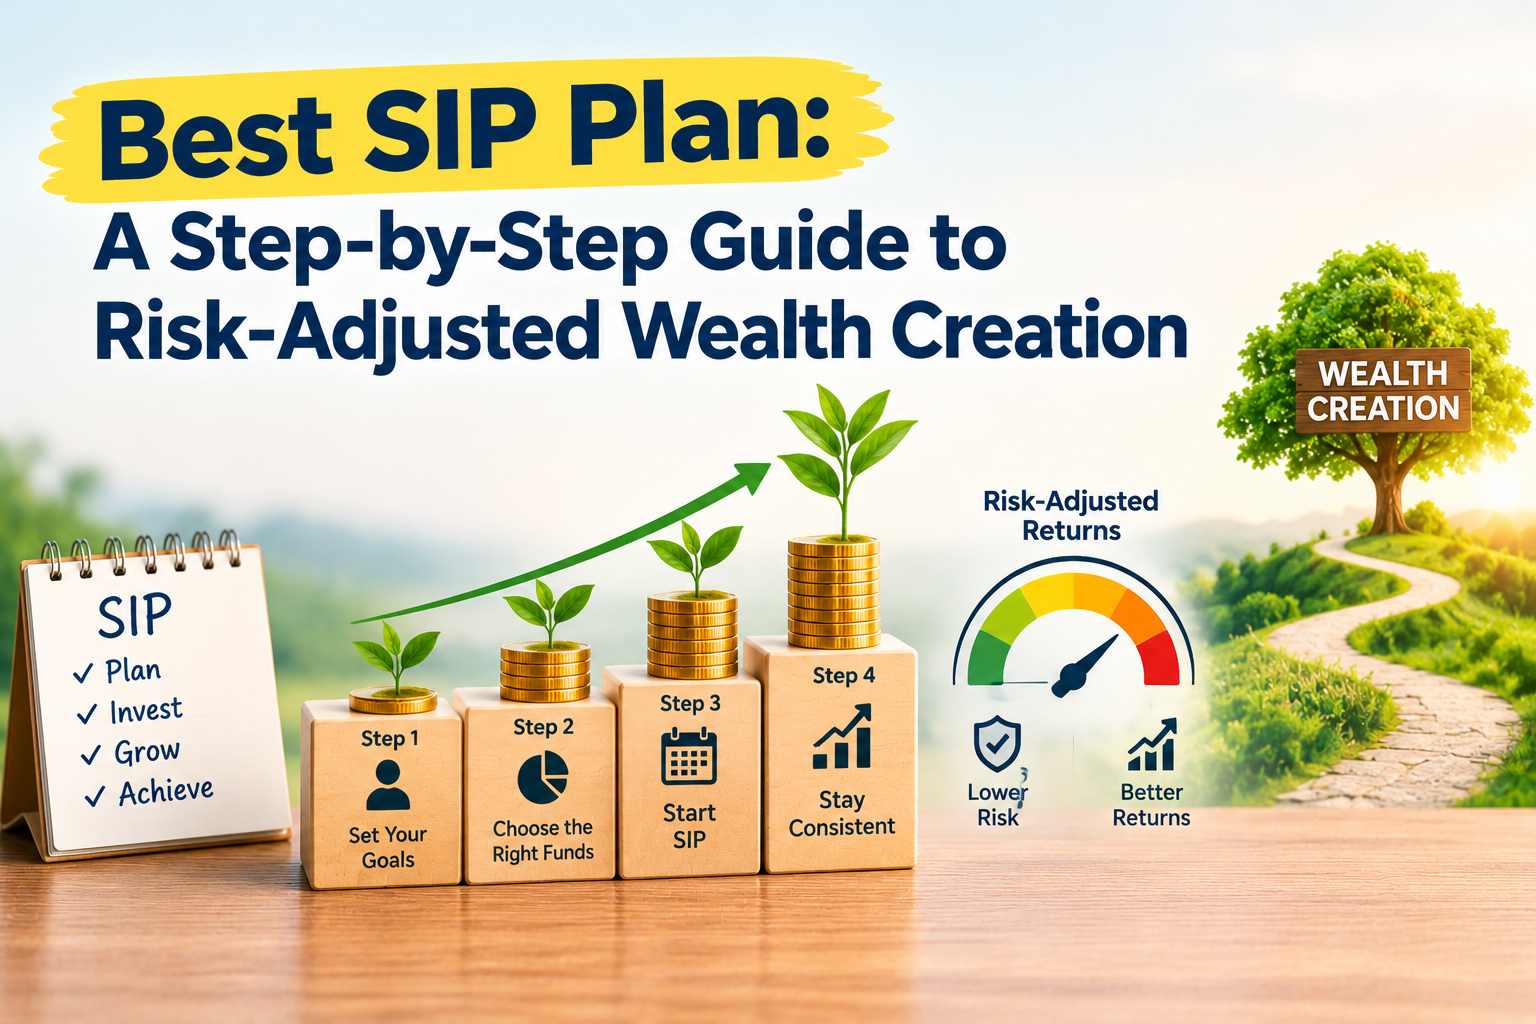
Seven years is the sweet spot a lot of seasoned investors quietly aim for with their SIPs — long enough for market swings to even out. A single equity fund works, but a four-part mix of mid-caps, US equities, gold, and a balancing fund smooths the ride considerably. Here's how to structure a 7-year SIP built for real-world market swings.
Quick answer, if you're in a hurry: A well-balanced 7-year SIP typically splits across four buckets: 20%–40% domestic mid-cap funds for growth, 10%–30% US equity funds for geographic diversification, 10%–20% gold funds as a hedge, and 20%–40% Balanced Advantage Funds for stability. Longer SIP horizons (7+ years) have historically shown far fewer negative-return periods than shorter ones — though that's a historical pattern, not a guarantee. |
Why 7 Years Changes the Risk Picture
Over 1–3 year windows, equity markets can and do turn negative — corrections happen, and short-term SIPs can land you in the red purely from bad timing. Stretch that horizon to 7 years or more, and history tells a different story: rolling return data on broad Indian indices shows markedly fewer negative-return periods the longer you stay invested, since monthly purchases average out both highs and lows (rupee-cost averaging).
Horizon | Typical Risk Profile |
1–3 years | High chance of short-term volatility or temporary loss |
5 years | Meaningfully lower downside risk, still some variability |
7+ years | Historically, very few negative-return periods on broad indices |
"Historically rare" isn't "impossible" — treat this as a strong tailwind for longer SIPs, not a guarantee against loss.
Pillar 1: Mid-Cap Funds — Your Growth Engine
Mid-cap companies (roughly ranked 101–250 by market size) have historically outgrown large-cap indices over long stretches, with sharper swings along the way — mid-cap indices spend a meaningful chunk of trading days sitting 10%+ below their recent peak. That volatility is the trade-off for extra growth. Keep mid-cap exposure to 20%–40% of your SIP via low-cost index funds or well-rated active funds, not more.
Pillar 2: US Equities — Spreading Your Bets Globally
Keeping all your money in Indian markets ties your wealth entirely to India's economic cycles. US equity funds (Nasdaq 100 or S&P 500) diversify that risk and add exposure to global tech leaders. There's a quiet bonus too: the rupee has historically depreciated against the dollar by roughly 3% a year, typically adding to Indian investors' returns on US assets. Aim for 10%–30% of your SIP here.

Illustrative long-term return ranges across asset classes — actual figures vary by time period and data source, and past performance never guarantees future results.
Pillar 3: Gold — Your Inflation and Crisis Hedge
Gold doesn't move in lockstep with equities — that's the point. It tends to hold or gain value during high inflation, currency weakness, or geopolitical shocks, the moments your equity holdings are most likely to wobble. Gold mutual funds let you SIP into gold without the storage costs or making charges of physical gold. A 10%–20% allocation is a reasonable hedge without diluting growth too much.
Pillar 4: Balanced Advantage Funds — Your Stability Cushion
Balanced Advantage Funds (BAFs) handle shifting between equity and debt for you. When markets look expensive, they typically pull equity exposure down (toward ~50%) and build debt; when markets correct, they lean back into equity (up to ~70–80%) to buy at lower valuations. Routing 20%–40% of your SIP here adds a built-in shock absorber without manual market-timing.
Putting It Together: The Four-Pillar Framework
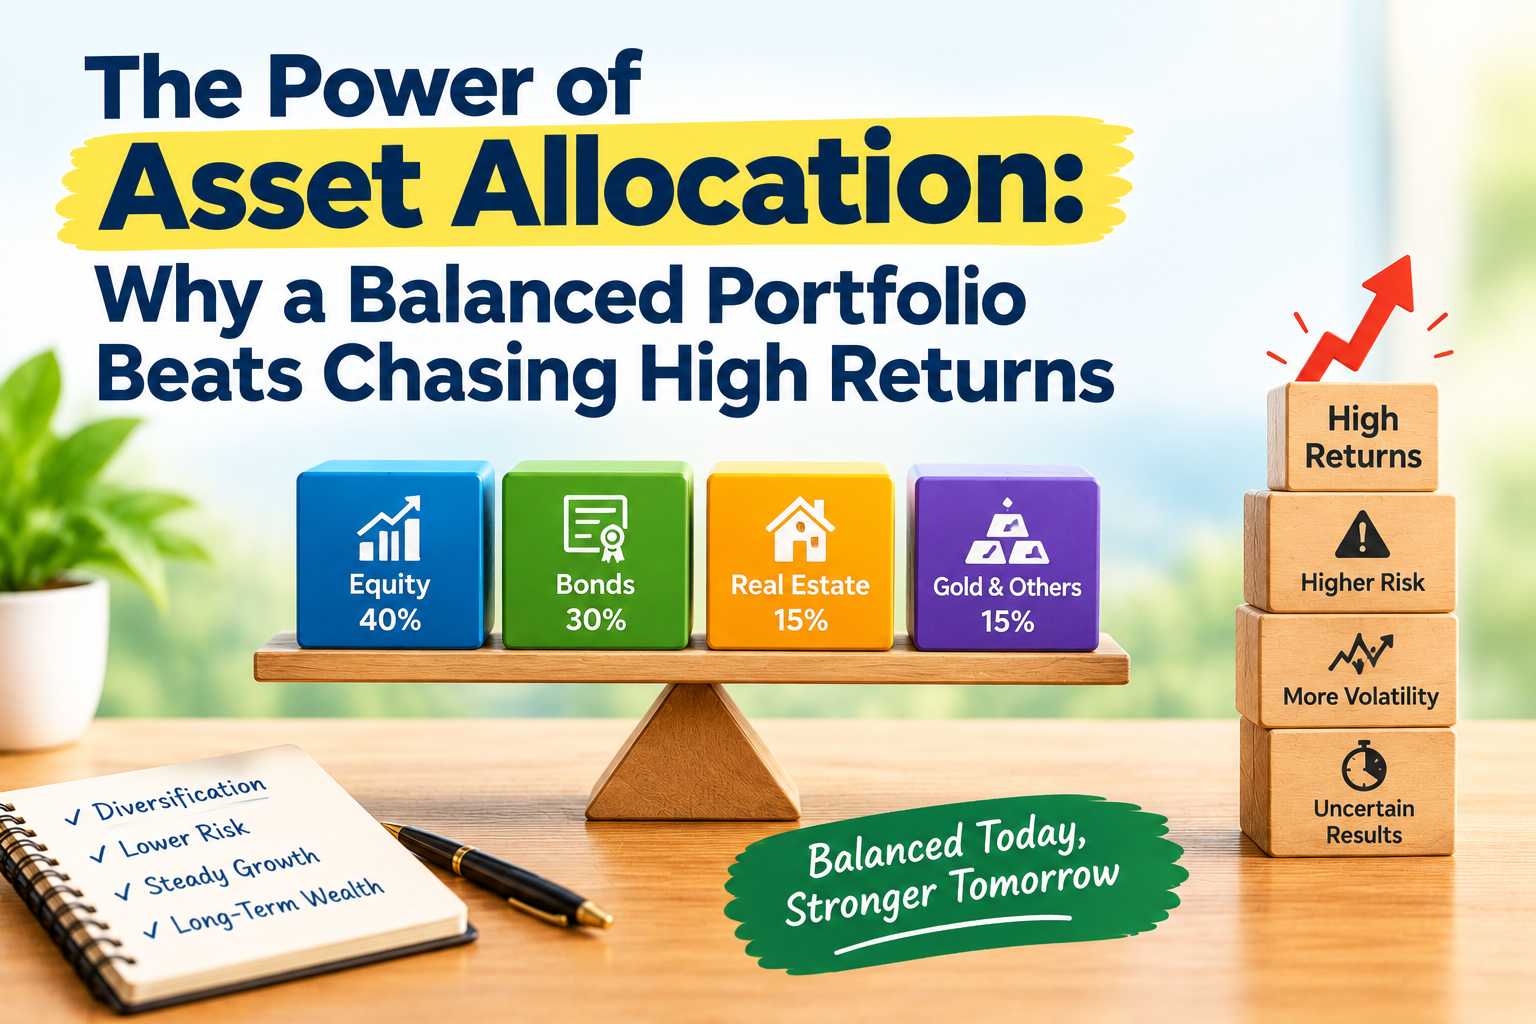
Rather than scattering your SIP across 15–20 overlapping funds, this four-bucket structure covers growth, geography, safety, and stability in one plan:
Pillar | Target Allocation | Role |
Mid-Cap Funds | 20%–40% | Domestic growth engine |
US Equity Funds | 10%–30% | Geographic diversification + currency hedge |
Gold Funds | 10%–20% | Inflation & crisis hedge |
Balanced Advantage Funds | 20%–40% | Dynamic rebalancing & downside cushion |
Frequently Asked Questions
Is a 7-year SIP really safer than a 3-year SIP?
Historically, yes — longer SIP horizons show far fewer negative-return periods on broad market indices, since monthly investing averages out highs and lows over more cycles. It reduces risk; it doesn't eliminate it.
Why include US equity funds in an Indian SIP portfolio?
They diversify away from India-specific risk and have historically benefited from US market growth plus long-term rupee depreciation — though both can work against you in any given year.
How many funds do I actually need for this strategy?
Usually just 4 — one each for mid-cap, US equity, gold, and a Balanced Advantage Fund. More funds within the same category mostly adds overlap, not diversification.
The Bottom Line
A single equity fund works for a 7-year SIP, but a four-pillar mix of mid-caps, US equities, gold, and a Balanced Advantage Fund is built to handle the swings a 7-year horizon will almost certainly bring. Stick to the ranges, review annually, and resist chasing whichever pillar had the best year.
Disclaimer This article is for general information only, not personalized financial or tax advice. Historical returns don't guarantee future performance. Consult a certified financial planner before investing. |