Debt Mutual Funds vs Fixed Deposits: Which Is Better for Investors?
Debt mutual funds with an SWP are usually more tax-efficient than fixed deposits, since only the gains portion of each withdrawal is taxed — not the whole amount. FDs still win on simplicity and guaranteed capital. But on a like-for-like ₹1 crore over 10 years, an FD investor could end up with roughly ₹16 lakh less.
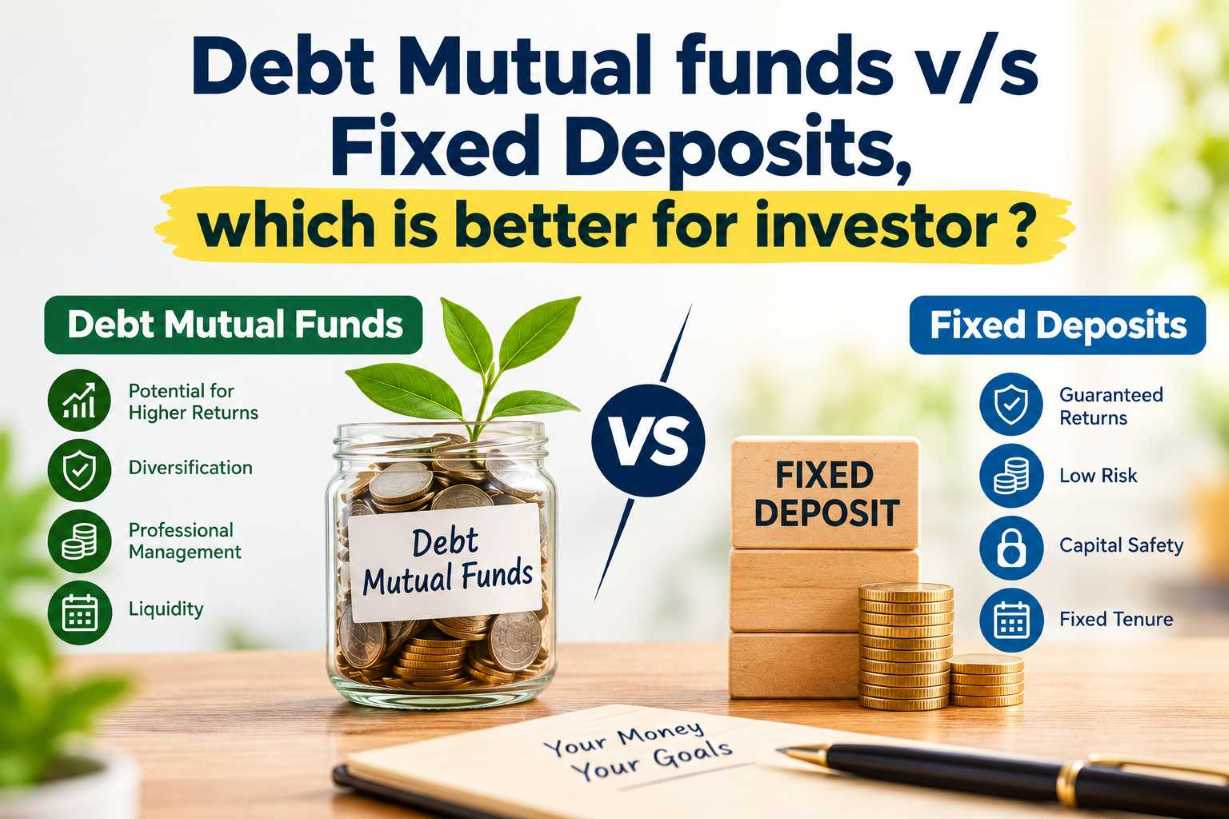
Debt Mutual Funds vs Fixed Deposits: Which Is Better for Investors?
Got a large lump sum sitting in a bank fixed deposit — maybe from a retirement payout, a PF settlement, or a property sale? You're probably prioritizing safety, and that's fair. But most FD investors never realize the biggest drag on their returns isn't market risk — it's tax. A debt mutual fund paired with a Systematic Withdrawal Plan (SWP) can generate the same steady income as an FD, while letting you keep a lot more of it. Explore why Debt Mutual Funds vs Fixed Deposits here.
Quick answer, if you're in a hurry: Debt mutual funds with an SWP are usually more tax-efficient than fixed deposits, since only the gains portion of each withdrawal is taxed — not the whole amount. FDs still win on simplicity and guaranteed capital. But on a like-for-like ₹1 crore over 10 years, an FD investor could end up with roughly ₹16 lakh less. |
Why Fixed Deposits Quietly Cost You More
In a fixed deposit, every rupee of interest gets added to your income and taxed at your slab rate — as high as 30% for many earners. Say you park ₹1 crore in an FD paying 8% a year:
FD Detail (₹1 Crore at 8%) | Amount |
Annual interest earned | ₹8,00,000 |
Tax paid every year (30% slab) | ₹2,40,000 |
Net annual income in hand | ₹5,60,000 |
Total tax paid over 10 years | ₹24,00,000 |
Total net income over 10 years | ₹56,00,000 |
That's nearly a third of your income going straight to tax every year — whether you need the money or not.
Debt Mutual Funds vs Fixed Deposits: The SWP Advantage
A debt mutual fund invests your money in bonds and similar fixed-income instruments, much like an FD does with a bank. The difference shows up when you withdraw. Every SWP payout splits into two parts:
Return of capital — your own original money, tax-free.
Capital gains — the actual profit, which is taxed.
Since tax applies only to the gains portion, your yearly tax bill on an SWP can be a fraction of what an FD charges for the same income.
Real Numbers: A 10-Year Income Comparison
Put the same ₹1 crore into a debt fund earning 8%, and withdraw ₹8 lakh a year via SWP instead of taking FD interest:
Debt Fund SWP Detail | Amount |
Tax paid in Year 1 | ₹17,778 |
Tax paid in Year 10 | ~₹1,28,000 |
Total tax paid over 10 years | ~₹7,90,000 |
Total net income over 10 years | ~₹72,00,000 |

Same ₹1 crore, same 8% return, same ₹8 lakh withdrawn each year — the SWP route keeps ₹16 lakh more in your hands.
The Extra Perk: Tax Deferral for Long-Term Growth
If you don't need regular income and just want your money to grow, debt funds offer another edge — no tax until you actually redeem. An FD deducts tax every year, shrinking what's left to compound. A growth-option debt fund lets your full return keep compounding, untouched, until you cash out.
Growth Option (₹1 Crore, 10 Years) | Final Value |
FD — interest reinvested, taxed yearly | ~₹1.72 crore |
Debt fund — tax deferred until redemption | ~₹1.81 crore |

Letting your money compound before paying tax adds close to ₹9 lakh in extra wealth over a decade.
Debt funds also let you offset capital losses from equity investments against these gains, trimming your tax bill further.
Risks You Shouldn't Ignore
NAV movement: unlike an FD's fixed capital, debt fund values shift daily with interest rate changes.
Credit risk: funds holding lower-rated bonds chase higher yields but risk default — stick to G-Secs and AAA-rated paper.
Rules can change: debt fund taxation has been revised before (most recently in 2023) and could change again.
FDs remain the simplest option: guaranteed returns and zero paperwork suit investors who value predictability over optimization.
Frequently Asked Questions
Are debt mutual funds safer than fixed deposits?
Not exactly "safer." FDs guarantee your capital, while debt fund values move slightly with interest rates and carry some credit risk. Debt funds win on tax efficiency, not capital certainty.
Is a debt fund SWP better than FD interest for monthly income?
For most investors in higher tax brackets, yes — only the gains portion of each SWP withdrawal is taxed, not the full amount like FD interest.
Do debt funds still offer a tax advantage after the 2023 rule change?
Debt funds bought after April 2023 are taxed at your slab rate on gains, same as FDs. But you're still taxed only on the gains portion of each withdrawal, not the entire amount — that's where the real saving comes from.
The Bottom Line
If tax efficiency and long-term compounding matter to you, and you're comfortable with some day-to-day price movement, a debt fund with an SWP will likely leave you with meaningfully more money than a comparable FD. If simplicity and a guaranteed number matter more, an FD remains reasonable — you're just paying a tax premium for that peace of mind.
Disclaimer This article is for general information only and isn't personalized financial, investment, or tax advice. Tax laws change and circumstances vary. Consult a certified financial planner or tax professional before investing. |